There is one success story that has risen above India’s divisions – the country’s instant real-time digital payments system, or Unified Payments Interface (UPI). Regardless of one’s political leanings, there is no disputing that UPI has transformed the way Indians pay for goods.
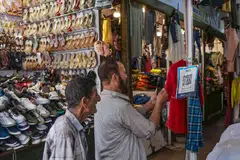
Whether it’s jewellery or jalebis, pants or pakodas, paying for goods no longer involves handling grubby old currency notes. Instead, a quick scan of the retailer’s QR code and a few taps on your smartphone app are all it takes. No fuss over figuring out how to return the exact change either.
The ease has proved addictive. From just 373 transactions in its first month after it was introduced in April 2016, the system has grown to over 24 billion transactions in September 2026. That’s more than 27,700 transactions in just the time it takes you to read this sentence.
What is even better is that the payments system has been free for users, both customers and merchants. But soon this will no longer be the case, with the authorities having paved the way for fees to keep UPI running, a decision that has thrown the payments system into the thick of a raging debate.
Starting on Oct 15, merchants will have to pay a charge of 0.4% for every transaction over Rs2,000 (about S$27). This merchant discount rate (MDR) has been capped at 300 rupees for transactions of Rs75,000 or more.
Payments of more than Rs2,000 for certain key services such as at petrol pumps and railways, on the other hand, involve a flat fee of five rupees. Customers, however, remain unaffected, and every person-to-person transfer, regardless of the amount, will also be free.
Small merchants – those with UPI QR-code receipts of less than Rs100,000 per month – will also continue to enjoy a mandatory zero-MDR rate.
What’s the fear?
The move has generated anger among merchants, many of whom operate in a low-margin business environment. This has prompted worries that they may pass on the cost to customers, thereby slowing UPI’s expansion in India and undermining the growth of a globally acknowledged exemplar of digital payments that has helped formalise large segments of India’s informal cash economy.
With about 554.9 million users on UPI, the system still has room left to grow in a country of more than 1.4 billion people. Any additional charge, including an indirect cost imposed on customers, risks pushing people back to cash, especially in India’s price-sensitive markets.
At the heart of this debate are merchants such as Akhilesh Kumar, the 38-year-old owner of a shoe shop in Delhi’s Sarojini Nagar market, who was waiting for customers one afternoon in September. Footfall has been low, he says, since the start of the war with Iran. “Business is already down, and now this extra fee will only deepen my losses,” Kumar laments.
A back-of-the-envelope calculation puts the additional cost to his business because of the new MDR at around Rs2,000 per month.
This, he says, will be difficult to cough up because of existing expenses such as wages for his staff and taxes, as well as charges he must pay card companies, among other costs.
MDRs for card payments range from 1.5% to 2.5% in India, which often prompts merchants to illegally demand an extra charge from customers or ask for payment in cash. Kumar, however, acknowledges that if he tries demanding extra payment from customers for using UPI – which accounts for seven out of every 10 transactions at his store – they will simply go to another shop.
“I will have to pay for this charge out of my pocket, what else?” he says, demanding that the authorities take steps to revoke the MDR on UPI payments.
Why pay?
Even though UPI has been free for its users, maintaining its infrastructure involves costs. According to one estimate, it costs as much as Rs207 billion each year to keep the system running, including expenses on infrastructure maintenance, server capacity, cybersecurity and banking networks.
Even in Brazil, where the retail digital instant payments system known as Pix is celebrated widely, businesses pay an average fee of 0.22% per transaction.
According to the National Payments Corporation of India, an umbrella organisation owned and operated by public and private banks that oversees the UPI system, the funds generated from the MDR will be used to enhance the efficiency of digital payments, as well as extend financial assistance to ecosystem players for merchant onboarding and incentivising the growth of the system.
Players here include the Walmart-backed PhonePe and Alphabet’s Google Pay, two platforms that together account for nearly 80 per cent of the country’s UPI transactions. Without a way to charge users for their services, not only do players have little incentive to innovate, but even basic services can suffer at times.
UPI has suffered from rare but recurring outages in recent years, increasing scrutiny of the system’s infrastructure and its ability to scale reliably. The longest such outage, lasting about 300 minutes, was in April 2025.
“Without people getting incentives or rewards for maintaining the system, this was only going to happen more and more,” says Anupam Manur, who teaches economics at the Takshashila Institution in Bengaluru.
He expects the new fee – which analysts project could generate about 200 billion rupees annually – to ensure UPI’s long-term reliability and sustainability, besides boosting innovation with products such as micro-credit loans on the platform.
But is it fair to get UPI users to pay when the system is already generating significant savings, possibly much more than what it takes to keep UPI running?
These savings include the reduced need to print currency notes and, as Ram Sewak Sharma, a retired Indian civil servant and former chairman of the Telecom Regulatory Authority of India, tells me, savings that banks accumulate from reductions in the costs of over-the-counter transactions or ATMs used to dispense currency notes.
Then there are bank earnings from additional funds that remain within the formal banking system as individuals keep money in their accounts to use on UPI rather than let it sit idle in their pockets as cash.
In fact, Sharma argues that savings from UPI are far higher than what it takes to keep the system running each year, so much so that he even thinks it is the government and banks that should be paying to run UPI, not merchants or individual users.
“Why should the consumers be charged for something that is not costing anything and which is benefiting the ecosystem so much?” he asks.
“My fear,” Sharma adds, “is that ultimately, people will end up paying and banks will end up enriching themselves.”
A situation where banks and corporates benefit more from UPI than individuals would be antithetical to the raison d’etre of UPI, which was built as public digital infrastructure with substantial government support.
Over the years, UPI has had an outsized influence, not only formalising large segments of India’s informal cash economy and ensuring better tax compliance, but also boosting the growth of small businesses and allowing people to transfer money with ease.
“There are multiple benefits (from the usage of UPI), and therefore I think the government must preserve those benefits and actually promote them rather than putting a charge, which is quite unjustified,” notes Sharma.
Proceed with caution
Irrespective of who pays for UPI’s upkeep, one thing is certain – the payments system is far too critical for stakeholders to botch it up. This means they must track the impact of these charges on the system to ensure that they are put to good use and UPI continues to flourish.
A key thing to watch out for is whether the metrics around familiar UPI bugbears – such as outages, transaction decline rates and long dispute resolution times – improve. “You have to demand accountability along with the money that they’re going to get,” says Takshashila Institution’s Manur, noting that banks and other stakeholders must make all relevant data publicly accessible.
And, if evidence shows that transaction growth has begun slowing down or perhaps even declining because of the new charges, the authorities should reconsider the MDR. “Nobody should be dogmatic about this,” adds Manur, suggesting a lower flat fee if needed. However, he cautions against making UPI free again, as it would be “the death knell of UPI, because no new innovation will happen”.
Another concern is the dominance of big players in the UPI ecosystem, which could end up hurting consumer interests in the long run.
“New fintech companies should be able to enter and compete without excessive regulatory burden while also having the flexibility to recover service costs from consumers,” notes Shrey Madaan, India country associate for Consumer Choice Center, a Washington-based non-profit organisation.
Moreover, the government has to be more sincere and honest in its communications about UPI, which it hasn’t been. In June 2025, it said that “speculation and claims that the MDR will be charged on UPI transactions are completely false, baseless, and misleading”, only to introduce it just a little more than a year later.
Users fear that current exemptions could be done away with next, or additional charges introduced. There are also concerns around claims that the fee has been introduced to address US grievances, as UPI has eaten into the market share of Visa and Mastercard in India, an allegation the government has denied.
For now, the MDR charges look set to kick in on Oct 15 despite sporadic protests and viral photos of posters showing merchants discouraging UPI payments. The authorities must ensure that UPI, something all Indians are genuinely proud of, continues to thrive and doesn’t become a victim of its success. THE STRAITS TIMES